| Feature of the digital economy | What it means | Planning use |
|---|---|---|
| Scope of the definition | Covers all producers and consumers, including government, that use digital inputs | Do not limit analysis or compliance planning to technology firms. Ordinary retailers, public bodies and service providers fall inside the definition. |
| Digital inputs | Digital technologies, digital infrastructure, digital services and data | List which of these inputs your product or policy depends on before comparing it with another business or country. |
| Cost structure | Lower costs in marketing, production and supply | Assume rivals can capture the same savings, and judge differentiation on other grounds such as audience, data or service quality. |
| Platform operators | Social media, online dating and online marketplaces that let users interact | Check how tax and competition rules treat the intermediary role, not only the goods or services that change hands. |
| Infrastructure providers | Cloud, data centre and telecom companies | Treat these as dependencies when assessing how exposed a digital service is to a handful of suppliers. |
| Alternative labels | Gig economy, on demand economy and platform economy | Match the label to the question: platform labor issues call for the narrower terms, while measurement and policy design need the broad one. |
The definitions and features above draw on the ILO thesaurus entry for the digital economy and an explainer from Sprintzeal.
The digital economy is all economic activity that relies on, or is significantly enhanced by, digital inputs such as technologies, infrastructure, services and data. How firms earn from it is shaped by tax, competition and labor rules.
For the wider rulebook, see our overview of digital economy policy. This guide concentrates on the practical consequences of those rules, then on how value is created, traded and measured.
Effects on businesses and consumers
The most direct effect is on cost. Sprintzeal’s explainer says the digital economy has made it possible to reduce costs for businesses in marketing, production and supply. A saving that any competitor can copy is a weak foundation for a business plan. Durable advantage has to come from something a rival cannot simply switch on, such as an established audience, a better service or the data a product generates.
The practical choices differ by the kind of participant:
- Sellers and retailers: e-commerce lets a business sell through electronic systems, so the decision is whether to sell through a marketplace or through its own channel. A marketplace offers reach, but the seller then operates under the platform’s terms and fees.
- Public bodies: because the definition covers government as both producer and consumer of digital inputs, public services and procurement belong in the same analysis as private firms.
- Firms that depend on cloud and telecom suppliers: infrastructure providers power the rest of the sector, so a service built on them inherits their strengths and their points of failure.
Platform work and the gig economy
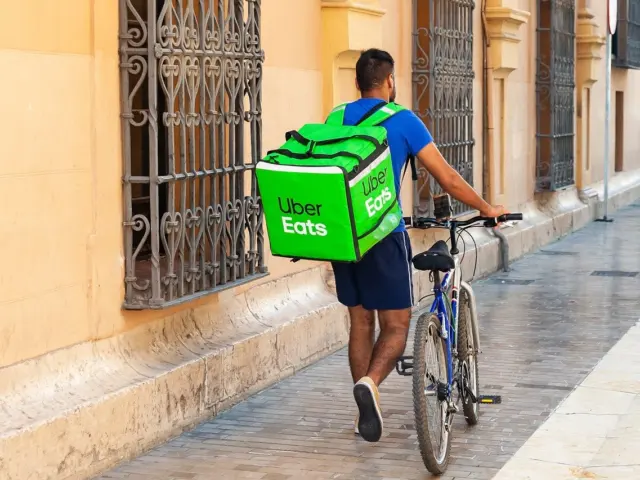
The ILO thesaurus lists gig economy, on demand economy and platform economy as alternative labels for the digital economy. They describe the part of it where an app matches people who want a service with people who supply it.
Sprintzeal’s explainer describes Uber as a company founded in 2009 that now provides service in 71 countries and more than 890 cities, and says it created the aggregator business model, in which an app connects riders and drivers. The same explainer says Airbnb, founded in 2008 and available in 220 countries and more than 100,000 cities, disrupted the traditional hotel industry and gave rise to the sharing economy.
The implication for policy is structural. An aggregator earns by sitting between two sides of a market. A labor rule that changes the terms on which drivers or hosts work therefore reaches the platform’s own revenue model, and so does a competition rule on how the platform treats its two sides. Anyone assessing such a business should read the labor and competition position before the headline growth figures.
How tax, competition and labor rules change the revenue model
Policy is not a neutral backdrop for digital businesses. A paper in the Sociostudies almanac notes that there is a broad range of definitions of the digital economy, and that national emphases differ. In the US the emphasis is on open and unlimited access to the internet, while in China the emphasis is on shared data use by government and commercial bodies. In December 2016 the President of Russia signed a decree on the Digital Economy Program. The same paper argues the digital economy should be viewed as an economy of agreed interests between the state, society, business and individuals.
Read together, these points mean the same business model can be more or less profitable depending on where it operates. Four levers matter most:
- Tax rules: a levy aimed at digital sales or services changes the margin on every sale it covers. Our guide to digital services tax explained sets out which countries tax big technology companies and how.
- Competition rules: limits on how an intermediary uses its position between buyers and sellers matter most to firms that rely on a platform for their customers. Those firms should check whether the rules protect their access or only the platform’s.
- Labor rules: where workers supply the service, classification and pay rules set a cost floor that no amount of software removes.
- Device and product rules: obligations on physical goods sit alongside the rules for online services. The guide titled Right To Repair Act Explained: What It Means For Consumers, Businesses, And Devices In 2026 – Technopolicy covers what repair rules mean for consumers, businesses and devices.
A sensible reading order for a founder or analyst is to start with the lever that touches the largest revenue line, then work down. A marketplace should look first at competition and tax. A labor-intensive app service should look first at labor rules.
How the digital economy is built
The most cited definition comes from the OECD, as recorded in the ILO thesaurus. It incorporates all economic activity reliant on, or significantly enhanced by, the use of digital inputs, including digital technologies, digital infrastructure, digital services and data. It refers to all producers and consumers, including government, that use those inputs. Because the definition is anchored in inputs rather than in a list of industries, a bakery that takes online orders and a cloud provider both fall within it.
Sprintzeal’s explainer sorts the operators into types. Platform providers are companies whose online platforms let users interact, such as social media, online dating and online marketplaces. Infrastructure providers supply the basic infrastructure that powers the digital economy, namely cloud, data centre and telecom companies. The first group earns from the interactions it hosts, which is why intermediary rules matter to it. The second earns from supplying capacity, which is why dependency and concentration matter to its customers.
The Sociostudies paper is clear that no single definition has settled the field. That is why two reports on the size of the sector can both be correct and still disagree: they may be counting different things.
Measuring the digital economy
The OECD addressed the disagreement with its 2020 roadmap toward a common framework for measuring the digital economy. The aim of a common framework is to let countries count the same inputs in the same way, so that comparisons across borders mean something.
A second approach is by component. Sprintzeal’s explainer says the American statistician and economist Thomas Mesenbourg identified the key components as e-business infrastructure, e-business and e-commerce. Measuring each separately shows whether growth is coming from the networks and tools, from firms using them internally, or from sales to customers.
Company-reported audience figures are a different kind of number. The same explainer states that Amazon has almost 600 million active users per month and that Netflix has over 222 million subscribers in 190 countries. These are reach metrics reported by or about individual firms. They show scale, but they do not measure output, value added or a country’s share of activity, so they should not be set beside national statistics without that caveat.
For a practical comparison, check three things before trusting any digital economy figure:
- The definition used: whether it follows the broad OECD input-based wording or a narrower list of industries.
- The unit: users, subscribers and countries served describe reach, while output and value added describe economic contribution.
- Who reports it: a statistical framework applied across a country differs from a single company’s own count.
Frequently asked questions
Is the gig economy the same as the digital economy?
Not exactly. The ILO thesaurus lists gig economy as an alternative label, alongside on demand economy and platform economy, but the full definition also covers government and any producer using digital inputs. Use the narrower labels when you mean platform work.
Does the digital economy include government?
Yes. The OECD-attributed definition recorded by the ILO refers to all producers and consumers, including government, that use digital inputs.
What counts as e-commerce?
E-commerce is the buying and selling of goods and services through electronic systems, according to Sprintzeal’s explainer. It is one component of the digital economy, not the whole of it.